
Buildings and contents insurance is relevant to anyone buying, remortgaging, or already living in a home who needs cover in place, particularly where buildings insurance is a condition of your mortgage offer.
Protection & insurance
Buildings & Contents Insurance
Buildings insurance covers the structure of your home, often a condition of your mortgage, while contents insurance covers what's inside it. We help you arrange both, so you're covered from the day you complete.
90+Lenders compared
FCAAuthorised & regulated
FreeInitial consultation
900+5.0 ★ Google rating
The basics
What do buildings and contents insurance cover?
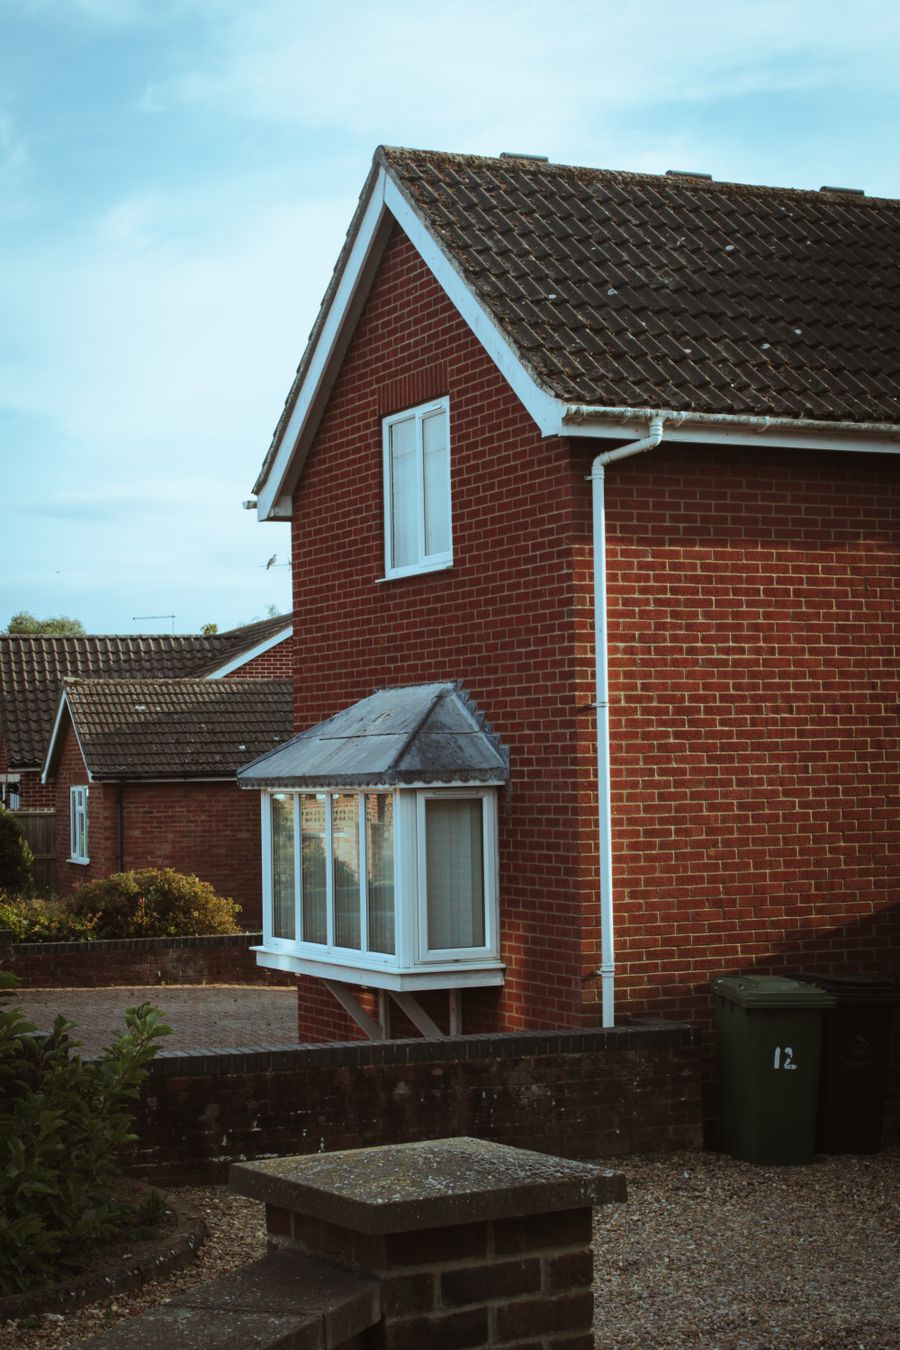
Buildings insurance covers the physical structure of your home, walls, roof, windows, doors and permanent fixtures, against risks like fire, flood, storm damage and subsidence. It's usually a condition of your mortgage, because the property is the lender's security as well as your home.
Contents insurance covers your possessions inside it, furniture, electronics, clothing and belongings, against loss, theft or damage. The two are often sold together, but they protect different things, and it's worth knowing what each one covers before assuming you're insured for something you're not.
Options available
Ways cover can be arranged
We compare these against your mortgage requirements, your property and what you need covered.
Buildings only
Covers just the structure. Useful if contents are already covered elsewhere, such as under a separate landlord or tenant policy.
Contents only
Covers only your possessions. Suitable for tenants or leaseholders where the buildings are covered by a freeholder or landlord.
Most common
Combined buildings & contents
One policy, one renewal date, often cheaper than two separate policies and simpler to manage.
Accidental damage add-on
Extends cover to damage you cause yourself, such as spilling paint on a carpet, which standard policies usually exclude.
How it works
Getting the right cover in place
Protection is arranged alongside your mortgage application, not as a separate, forgotten task. This is how we handle it.
- 1
A free cover review
We talk through your property, what's in it, and any specific items or risks you want covered.
- 2
Comparing providers and cover levels
We compare providers on rebuild cost, contents cover level and any specified items, rather than just headline price.
- 3
Cover arranged for completion day
We arrange your policy to start on the day you legally complete, meeting your lender's requirement without you having to chase it.
Common questions
Buildings & Contents Insurance questions, answered
Most mortgage lenders require buildings insurance to be in place from the day you legally complete, since the property is their security as well as your home.
Buildings insurance covers the structure of your home, walls, roof, windows and fixtures. Contents insurance covers your possessions inside it, such as furniture, electronics and belongings.
Yes, most providers offer combined policies, and it's often more convenient and cost-effective than arranging them separately. We'll compare both options for you.
If you're renting, your landlord is normally responsible for buildings insurance, but their policy won't cover your own possessions. Contents insurance is worth considering to protect your belongings against theft, fire or accidental damage.
Standard buildings and contents policies typically exclude damage you cause yourself, such as spilling something or accidentally putting a foot through a ceiling. Accidental damage cover is an optional add-on that extends your policy to include this.
Most standard policies include cover for storm, flood and subsidence, but the level of cover, and any excess that applies, varies by provider and by the flood risk of your specific property, so it's worth checking rather than assuming.
Cost depends on the rebuild value of your home, its location, the level of contents cover and any add-ons you choose, but we'll compare providers to find a competitive quote.
Who this is for
Cover for your home and what's in it
Providers we compare
Whole-of-market, not tied to one insurer
We compare home insurance across leading UK providers, including:


Provider panel shown for illustration and reviewed regularly; availability depends on your circumstances and the specific product. Logos are the property of their respective owners and do not imply endorsement of City Mortgage Solutions Limited.
Example scenario
Illustrating how this can help
A worked example of the kind of outcome buildings and contents insurance is designed for. This is an illustrative scenario, not a specific client, and every case is assessed on its own facts.
Example, not a real client
A burst pipe over Christmas
A homeowner returned from holiday to find a burst pipe had flooded her kitchen and the room below, damaging the ceiling, flooring and several appliances. Because she had combined buildings and contents cover in place, arranged when she took out her mortgage, both the structural repairs and the damaged contents were covered under the same claim, and the insurer arranged alternative accommodation while the work was carried out, keeping cost out of the picture during an already stressful time.
- Situation
- Burst pipe, flooding to kitchen and room below
- Cover arranged
- Combined buildings & contents insurance
- Outcome
- Repairs, contents and alternative accommodation all covered
Related cover
Other cover you might need
Life assurance
A tax-free lump sum, or an ongoing income, to your family if you die during the policy term, so your mortgage and household costs are covered.
Critical illness cover
A tax-free lump sum if you're diagnosed with a specified serious illness, such as cancer, heart attack or stroke, while you're still alive, giving you space to recover without money worries.
Income protection (PHI)
A regular monthly payment that replaces part of your income if illness or injury stops you working, covering the one thing most people forget to insure: their salary.
Private medical insurance
Faster access to private diagnosis and treatment, so you're not waiting on an NHS list, with the ability to choose where and when you're seen.
Business insurance
Protection for self-employed people, contractors and small business owners, and the income their mortgage relies on.
Guides
Buildings & Contents Insurance guides
GuideDo I need buildings insurance to get a mortgage?Why most lenders won't complete without it in place.GuideBuildings vs contents insurance, do I need both?What each one actually protects.GuideHow is my buildings insurance rebuild cost worked out?Why it isn't the same as your property's market value.
What our customers say
Reviewed by real clients on Google
Free, no-obligation consultation
Start your protection & insurance journey
Tell us when suits and we’ll call you back. Message us on WhatsApp.
Fancy a chat?
Thanks, request received.
We'll be in touch within one working day.